

At this time’s Basic is republished from Doctor On Hearth. You may see the unique right here.
Take pleasure in!
How does one usually take into consideration cash? How ought to one take into consideration cash?
The reply to the primary query, no less than for me, has usually been what cash can purchase. For lots of years, cash purchased me stuff.
In grade faculty, cash purchased me soccer playing cards and sweet. In highschool, cash paid for motion pictures and first dates. There might have even been a second date one time, however that’s not essential.
In school, cash paid for tuition and beer. I additionally spent cash on meals, clothes, fuel, lease, and extra beer. The older you get, the extra issues there are to purchase along with your cash. Furnishings, televisions, stereos, fuel grills, prompt pots, electrical bikes, curling sneakers, you title it. You additionally want some shelter for your self, your loved ones, and all that stuff.
Finally, although, you get to a degree the place you understand you’ve already purchased all of the issues you could reside a cheerful, productive, and environment friendly life. In truth, for those who’re like me or any of the hundreds of thousands of different non-minimalists on the market, you’ve purchased way more than you’re ever going to want.
While you attain that place in maturity the place you understand shopping for extra stuff or buying alternative issues for the superbly acceptable belongings you already personal is pointless, it’s time to reframe the best way you concentrate on cash.
Fortuitously, there’s a guide for that.
After studying The White Coat Investor’s Evaluation over a 12 months in the past, I knew this was a guide I wanted to learn. I’ve loved following writer Jonathan Clements‘ work on The Humble Greenback, and he’s obtained a stellar resume, having written for The Wall Avenue Journal for greater than 20 years. It didn’t damage that Dr. Dahle stated it may be one of the best monetary guide he’s learn in 5 years.
What attracted me to the guide wasn’t the writer’s expertise and popularity, however moderately his message. As I learn that evaluation, I stored nodding and nodding and considering Sure, Sure, 100 occasions Sure!
I reached out to Mr. Clements by way of Twitter (@ClementsMoney), instructed him how a lot I knew I might love the guide, and the way I’d be glad to jot down a evaluation of my very own, and he kindly despatched me a personalised copy.
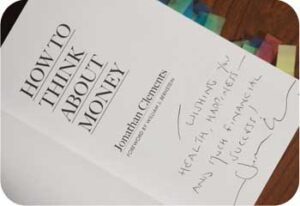
That was a very long time in the past, and I later had the pleasure of assembly the beneficiant man who despatched me that guide at our mutual good friend Dr. Jim Dahle’s convention. I figured I had higher ship on the promise I made many moons in the past and write that guide evaluation previous to assembly him. Therefore, this publish.
How We Suppose About Cash
How To Suppose About Cash was one huge serving to of affirmation bias for a man like me.
Clearly, Mr. Clements and I believe alike in terms of cash, and it might be as a result of we’re studying the identical reference materials and imagine in evidence-based cash administration, however I imagine there’s extra to it than that. There’s a sure mindset that some folks embrace and others will soundly reject it doesn’t matter what expertise or analysis suggests.
The philosophies mentioned within the guide are pretty frequent on the pages of the blogs and books I learn, however moderately unusual in day-to-day life for the common American and doubtless extra uncommon for the standard doctor. What kind of philosophies?
- Reside effectively under your means.
- Save early and infrequently, prioritizing retirement financial savings above all.
- Spending on luxuries gained’t result in long-term happiness
- Hold Investing easy. Passive revenue funds are your good friend.
- Function and accomplishment are fulfilling earlier than and after retirement.
- Psychology explains loads of poor cash administration. Understanding our biases and weaknesses can result in higher resolution making.
- Freedom is without doubt one of the greatest issues cash can purchase.
Highlights from How We Suppose About Cash
There are extra gems than I might presumably checklist in a guide report, they usually begin earlier than Mr. Clements get a flip. From retired neurologist Dr. William Bernstein’s foreword:
“On the floor, all of it appears so apparent: We want cash to purchase the stuff that can make us glad. No, no, and no once more. At first, cash buys time and autonomy. Secondarily, it buys experiences. Final, and least, it buys stuff, and as a rule, the stuff we purchase makes us depressing.”
Amen.
Mr. Clements does an amazing job of highlighting the teachings gleaned from dozens of educational research on cash and happiness. Among the many findings are that cash doesn’t purchase as a lot happiness as we might assume, we overvalue objects and undervalue experiences, spending on others makes us glad, youngsters don’t convey as a lot pleasure as we dad and mom declare, and life satisfaction troughs in a single’s forties.
I’m in my forties, and if that is as dangerous as life goes to get, I take into account myself very lucky, to not point out glad.
The hedonic treadmill will get applicable remedy, the advantages of a brief commute had been featured (the morning and afternoon commutes had been two of the three most disturbing of 19 every day actions in a single examine), and the significance of connecting with household and associates had been touted pretty much as good for each happiness and well being.
On shopping for freedom:
“After I speak to varsity college students, I don’t inform them to comply with their goals. As an alternative, I inform them to deal with making and saving cash. I even recommend that they could intentionally go for a much less attention-grabbing however higher-paying job, to allow them to sock away critical sums of cash.”
He goes on to say there will likely be time to pursue your passions, and also you’ll be higher outfitted to take action with out trepidation while you’re a bit older and extra financially safe. Sound recommendation, I say.
Cash Discuss
As soon as once more, investing is a subject on which we see eye to eye. He talks about the tyranny of funding charges, the advantages of delaying social safety, and the gorgeous simplicity of a three fund portfolio.
Referencing The Millionaire Subsequent Door, he reiterates the truth that outward shows of wealth are higher indicators of an individual’s spending moderately than their web value. Most of the actually rich are working towards stealth wealth, mixing in with their neighbors in an unassuming approach.
The 4% rule isn’t ignored; though it’s not prominently featured, both. He does, a lot to my dismay, point out a special rule of thumb that states you’ll need about 80% of your pre-retirement revenue to reside effectively in retirement.
Whereas that math makes some sense for these with bizarre incomes and comparatively low financial savings charges, I nonetheless discover it irritating and deceptive when retirement wants are matched to pre-retirement revenue moderately than pre-retirement spending, when the latter is the one one of many two that play a task in figuring out your wants.
The textual content does an excellent job reviewing what it means to personal shares and bonds, and what you’ll be able to anticipate in returns from every. He additionally discusses methods to keep away from dropping your hard-earned cash shortly by correctly insuring your self from potential catastrophes
The place We Differ
While you’ve obtained a lot frequent floor, it’s robust to provide you with many factors of competition, however since I write for a special crowd, specifically high-income professionals with an curiosity in early monetary independence, I used to be truly in a position to provide you with just a few.
Early retirement doesn’t come up an entire lot, however when it did, right here’s what the writer needed to say:
“We’d attempt to purchase a house in our 30s. In our 40s, our focus typically switches to the youngsters’ school schooling. With these two targets behind us, we may be in our 50s– and it’s too late, as a result of 10 to fifteen years merely isn’t sufficient time to build up the cash wanted for a snug retirement.”
Since we turned financially impartial inside a decade on one revenue with out understanding what FI was, I’ve to name shenanigans on that final line. My tweet on the topic:
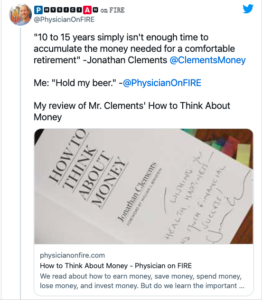
When the prospect of early retirement comes up one other time, he says:
“Now and again, after I was at The Wall Avenue Journal, I might obtain emails from readers, boasting about how that they had managed to retire of their 40s. I might instantly write again, asking a single query, “Do you may have youngsters?” The reply was nearly all the time “no.””
Whereas I agree that youngsters could make early retirement tougher, they shouldn’t add various years for somebody with an amazing financial savings price and excessive revenue, and the presence of kids is usually a nice motivating issue to make you need to turn out to be financially impartial earlier than they’ve flown the coop.
Talking of financial savings charges, Mr. Clements recommends protecting “mounted prices” at half of gross pay. Be aware that this doesn’t embody discretionary bills like journey and different experiences, and even good beer.
Dwelling mortgage-free, I’ve estimated our core (mounted) bills to be about $40,000 a 12 months and our discretionary bills at about $30,000 a 12 months. If I had an $80,000 wage, I’d be abiding by his rule of thumb, most likely paying about $10,000 in taxes, and saving nothing for retirement.
If we take a extra typical doctor family revenue of $300,000 12 months (just like the docs in the story of 4 physicians), you’d have mounted bills of $150,000, let’s say discretionary bills conservatively equal to ours at $30,000 a 12 months, and taxes of $100,000. You’re solely saving $20,000 a 12 months in direction of retirement, or lower than 7% of gross revenue, which isn’t almost sufficient.
I believe it makes extra sense to base an applicable financial savings or spending price on after-tax pay. We are able to’t spend or save the portion that goes to Uncle Sam, so go away that piece out of the equation. I encourage these pursuing monetary independence to attempt to reside on half their take house pay, utilizing the remaining to pay down debt or make investments.
Who Ought to Learn How To Suppose About Cash
You.
Your companion.
Your youngsters once they’re sufficiently old.
I believe the folks that can profit probably the most from this guide embody:
- Individuals simply coming into cash (beginning a profession)
- Those that have been making an attempt to purchase happiness (it doesn’t work like that)
- Somebody who exhibits little curiosity in cash (to allow them to be taught why cash issues)
- A spendthrift who doesn’t see the issue in dwelling paycheck to paycheck
- Debt-ridden people struggling to remain afloat or get forward
The guide is loaded with data nuggets that merely reaffirmed my beliefs, however might profoundly change the best way others take into consideration cash.
He closes with a recap, providing twelve strategies to get probably the most out of your cash. I gained’t spoil it for you or plagiarize by itemizing all of them, however I’ll go away you with a portion of the ultimate one.
“The aim isn’t to get wealthy. Fairly, the aim is to find the money for to steer the life we would like.”
I couldn’t have stated it higher myself.
Would you want a duplicate of this guide? Nice! Choose one up right here.