

To not point out, fluctuating dwelling values can considerably influence your monetary scenario, particularly if the market developments result in a lower in dwelling values over time, additional compounding the monetary burden on owners.
When you transfer once more inside a brief interval—for instance, 4 years—all these charges will dwarf any fairness beneficial properties you might have. Think about driving a automobile off the lot: Everyone knows that it immediately loses worth. The identical is true of your own home, and it takes time to amortize (or unfold) the prices.
Most individuals keep of their home for lower than 8 years, and that quantity is the very best it’s been in a number of many years! Earlier than the 2008 monetary disaster, the common size of time People stayed put was round 4 years.
Don’t give in to see stress to purchase a home for those who may not keep there for the long run. If you understand you’ll transfer in fewer than 10 years, you’ll seemingly make more cash by renting and investing in S&P index funds.
-
Frequent mistake: “I’m not shifting for a couple of years. I can purchase so I don’t throw cash away on lease!”
-
Actuality: When you purchase for a brief interval, while you think about all prices, you’ll virtually actually lose cash.
Is your complete month-to-month housing value decrease than 28% of your gross month-to-month revenue?
Your complete housing prices must be lower than 28% of your gross revenue, together with your month-to-month mortgage funds. When housing prices exceed 28%, you threat being overwhelmed with bills if one thing goes unsuitable (e.g., an surprising restore, job loss, and so on.) Use the 28/36 Rule to see for those who can afford your housing.
Right here’s an instance:
-
Assume you make $10,000/month (that’s $120,000 per 12 months gross or earlier than taxes).
-
Assume your complete housing prices are $2,000 per thirty days, together with month-to-month mortgage funds. Nice! Your housing prices you 20% of your gross revenue. You cross this take a look at, and you may afford your housing.
-
Observe that complete housing prices embody all the things: taxes, curiosity, upkeep, furnishings, electrical energy, water, and even the roof restore 7 years from now (undertaking it).
Evaluating the affordability of month-to-month funds is essential within the context of total monetary planning for a home buy. It helps in assessing whether or not you may keep your way of life with out compromising on different monetary targets.
Why gross revenue? I take advantage of gross as a result of it’s straightforward to calculate. Everybody is aware of their gross revenue, and taxes complicate web revenue (totally different individuals select totally different deductions). Nevertheless, for those who want to make use of web revenue, go for it! I like when individuals create their very own factors of view on their funds.
Exceptions to the 28/36 rule
- When you dwell in an HCOL (excessive value of residing) space like NYC or Los Angeles, many individuals stretch the 28% quantity to 35% and even 40%.
- When you’ve got no debt (e.g., no automobile cost, scholar loans, or bank card debt), you would possibly stretch the numbers a little bit. I’d contemplate going to round 33%, however I’m conservative with my funds.
- In case your revenue in all fairness anticipated to go up quickly, reminiscent of with a job promotion, chances are you’ll stretch the numbers a little bit. Once more, I’d conservatively contemplate going to 33%… possibly.
Have you ever saved a 20% down cost?
When you haven’t saved a 20% down cost, you’re not prepared to purchase a home.
Why? Not simply due to PMI, which is an extra charge you’ll usually pay while you get a mortgage with out 20% down.
The true motive to avoid wasting 20% earlier than shopping for is counterintuitive: constructing the behavior of saving is vital earlier than you purchase and have surprising housing bills reminiscent of a damaged water heater, roof, or surprising taxes.
I continuously get annoyed feedback about how “impractical” this rule is. “How am I supposed to avoid wasting 20%? That may take years!”
Sure, it’ll—which is strictly why you must save now. Saving is a behavior that’s higher practiced earlier than your mortgage is in danger. Moreover, consulting with varied mortgage lenders to seek out the perfect mortgage phrases and charges can considerably influence your monetary planning. The Federal Reserve performs an important position in influencing rates of interest, which may have an effect on how a lot it’s good to save for a down cost, highlighting the significance of understanding the broader financial elements at play.
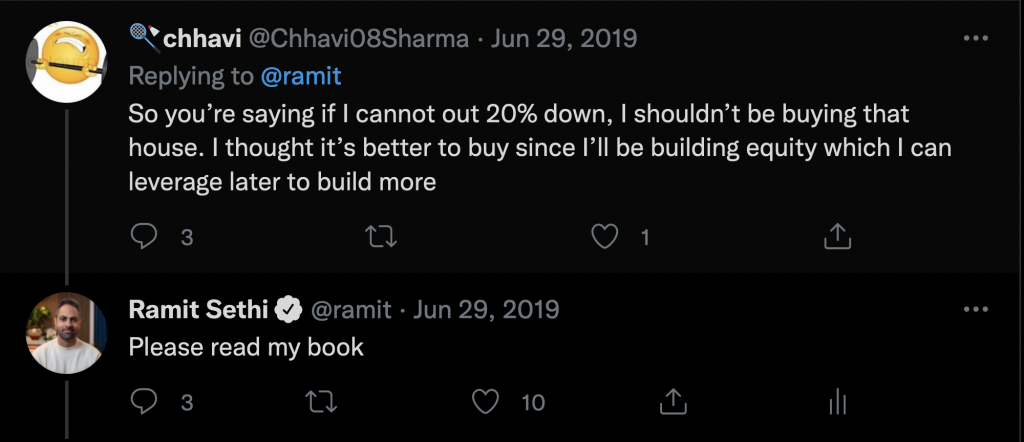
When you write a remark like this, you aren’t prepared to purchase a home.
Observe: I don’t imply that you need to put 20% down. In some instances, reminiscent of low rates of interest, many individuals deliberately select to place a small quantity down. However you must be capable to.
Are you OK if the worth of your own home goes down?
If you’re shopping for since you consider dwelling costs all the time go up, rethink: fluctuations in dwelling costs can considerably influence your funding, indicating that actual property just isn’t all the time the perfect funding.
Listed here are some good causes to purchase a home
- You’ve got youngsters, and also you wish to keep in your space or faculty district and construct recollections in the identical home for at the very least 10 years 👨👩👦👦
- Your mother and father are shifting in with you 🧓
- You wish to design a home collectively together with your partner 📐
- You like repairing and tinkering with a home and making it your individual 🔨
- You simply wish to! 🫰
Discover what’s not on the listing: “You want the worth of the home to go up”. Possibly it’ll—in that case, nice! Possibly, when you think about bills and alternative prices, you may have gotten a a lot better return in a easy S&P index fund.
Purchase for the correct causes!
Are you enthusiastic about shopping for?
When you’re approaching shopping for a home with dread—like a heavy feeling of obligation or peer stress—simply cease. You don’t want to purchase and you must by no means really feel responsible about renting. I lease by selection. On this video I discuss why.