

Your credit standing (or credit score rating) provides lenders an thought of how dangerous you might be to lend to. However totally different bureaus use totally different credit standing scales. We’re going to check out the most typical scale, FICO and present you the way these little numbers can affect your capacity to reside a Wealthy Life.
| Credit score rating | What it means |
| 800 – 850 | Nice. |
| 740 – 799 | Good. |
| 670 – 739 | Okay. |
| 580 – 669 | Dangerous. |
| 300 – 579 | OMG. |
In case your credit score rating is excessive, anticipate nice rates of interest on house loans, near-universal approval for bank cards, and an superior relationship life (it’s true: the next credit score rating predicts a greater relationship life).
If it’s low … properly, don’t fear. As a result of I’m going to point out you a system to alter that.
What’s the credit standing scale?
The credit standing scale is a measure that helps lenders decide whether or not or not they need to lend you one thing.
Your credit score rating impacts rates of interest, bank card approvals, and even issues like whether or not or not you’ll get authorized to hire flats.
Whereas there are totally different sorts of credit standing scales for people, probably the most generally used one is the FICO rating. FICO stands for Truthful Isaac Company. They’re an information firm that based the credit score scoring system again within the late-eighties.
Their scores are on a variety between 300 and 850 and are decided by info discovered on a person’s credit score report. And there are THREE main credit score bureaus that present these stories:
This implies you’ll be able to have three totally different credit score scores at any time. Granted, the scores gained’t sometimes differ that a lot from bureau to bureau.
The next items of knowledge decide your precise rating (courtesy of Wells Fargo):
- Cost historical past: 35%
- Quantities owed: 30%
- Size of credit score historical past: 15%
- What number of kinds of credit score in use: 10%
- Account inquiries: 10%
Keep in mind: The upper your rating, the higher it’s for you.
Why does it matter?
Right here’s a credit score rating chart with ranges courtesy of Experian — and what they imply for you:
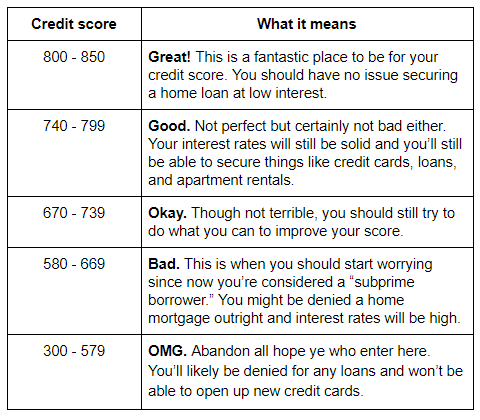
| Credit score rating | What it means |
| 800 – 850 | Nice! This can be a improbable place to be in your credit score rating. You shouldn’t have any problem securing a house mortgage at low curiosity. |
| 740 – 799 | Good. Not good however definitely not unhealthy both. Your rates of interest will nonetheless be strong and also you’ll nonetheless be capable of safe issues like bank cards, loans, and residence leases. |
| 670 – 739 | Okay. Although not horrible, it is best to nonetheless attempt to do what you’ll be able to to enhance your rating. |
| 580 – 669 | Dangerous. That is when it is best to begin worrying since now you’re thought-about a “subprime borrower.” You may be denied a house mortgage outright and rates of interest will probably be excessive. |
| 300 – 579 | OMG. Abandon all hope ye who enter right here. You’ll probably be denied for any loans and gained’t be capable of open up new bank cards. |
So in the event you’re planning on taking out a mortgage or attaining credit score of ANY form, you’re going to wish to be sure that your credit score rating is in examine. For those who don’t, you would possibly end up saddled with excessive rates of interest and being denied easy loans.
How do I examine my credit standing?
To examine your credit score rating, you’ll must journey 1000’s of miles by means of the 9 ranges of hell, Mordor, Siberia within the winter, AND make it previous the topiary maze from “The Shining” earlier than fixing a collection of riddles from a sphinx who will let you know your credit score rating in a useless language.
Oh wait, I’m sorry. That’s a typo. I meant checking your credit score rating is extremely easy. In truth, there are a TON of websites on the market that’ll offer you your credit score rating without cost.
Two good ones I counsel: Credit score Karma and Mint.
Head to those websites and comply with their directions. Be ready to enter primary information about your self (title, DOB, social safety #, and so forth.).
For those who discover that your credit score rating is nice, congrats! Do all you’ll be able to to keep that rating (I get to that under).
In case your credit score rating is low although, haven’t any concern. Right here’s a system that’ll assist you to enhance your credit score rating.
The best way to enhance your credit score rating
Bettering your credit score rating is all about 80/20 — do a small quantity of labor now and it’ll repay in spades later.
And also you don’t must do something loopy both. In truth, listed here are 5 keys that’ll assist you to transfer the needle in your credit score rating:
- Delete your debt
- Preserve your playing cards
- Negotiate your restrict
- Automate your pay
1. Delete your debt
Debt is likely one of the BIGGEST boundaries stopping folks from residing a Wealthy Life. That’s why if you’d like to have the ability to begin focusing extra of your vitality on incomes extra money and investing, you want to delete your debt.
You are able to do this utilizing my four-step system on getting out of debt quick.
2. Preserve your playing cards
Lots of people erroneously consider that they should get rid of their bank cards to enhance their rating. In spite of everything, bank cards are the explanation folks get bad credit report scores. It will stand to cause that closing the accounts enhance it … proper?
Incorrect. So very, very improper.
Why? As a result of 15% of your credit score rating is decided by your credit score historical past. So in the event you shut accounts, you shut that historical past.
This additionally negatively impacts your “credit score utilization charge” (extra on that later).
After all, there are going to be occasions whenever you simply want to shut a bank card (journey hacking, rates of interest too excessive, and so forth.). That’s superb so so long as you additionally be sure you’re not making use of to a serious mortgage inside six months of closing it.
You need as a lot credit score as attainable whenever you apply for loans.
Normally although, maintain your playing cards open and put a recurring cost on them. This exhibits that your playing cards are lively and retains your credit score historical past wholesome.
3. Negotiate your restrict
Your credit score utilization charge impacts 30% of your credit score rating because it impacts the quantity you owe.
And the formulation for it’s easy:
In contrast to your credit score rating, the decrease THIS quantity is, the higher.
Let’s take a look at an instance: For those who carry $1,000 debt throughout two bank cards with $2,500 credit score limits every, your credit score utilization charge is 20% ($1,000 debt / $5,000 complete credit score accessible).
For those who shut one of many playing cards, abruptly your credit score utilization charge jumps to 40% ($1,000 / $2,500). However in the event you paid off $500 in debt, your utilization charge could be 20% ($500 / $2,500) and your rating wouldn’t change.
When your credit score utilization charge is low, it exhibits lenders that you just don’t sometimes spend all the cash you will have accessible in your credit score — which suggests you probably gained’t default and so they gained’t lose cash.
You possibly can enhance your credit score utilization in two methods:
- Don’t carry numerous debt in your bank cards.
- Improve the quantity of credit score accessible to you.
I counsel requesting a credit score restrict enhance each six to 12 months. Solely do that if/whenever you’re out of debt although.
4. Automate your funds
Let’s speak about my FAVORITE topic on the planet: Automating your private finance.
That is IWT’s confirmed system that does various superior issues:
- Will get you out of debt.
- Helps you save for something.
- Earns you cash.
The most effective half? You do all of this passively. Which means there’s no problem of shifting your cash round, and no ache from seeing your cash half from you.
And since 35% of your credit score rating is decided by your cost historical past, it’s necessary to automate your system so that you pay your invoice on time and in full every month.
For extra info on methods to automate your funds, take a look at my 12-minute video the place I’m going by means of the precise course of with you.
It is best to ideally be paying off your total bank card stability every month, however in the event you can’t, you’ll be able to nonetheless enhance your rating by paying a minimum of the minimums, on time, each month.
What’s the good credit score rating?
The right credit score rating is wherever between 800 and 850.
That’s based mostly on a variety developed by an information firm referred to as FICO [Fair Isaac Corporation].
NOTE: There are different credit score rating ranges on the market (one even goes as excessive as 900). However probably the most generally used one is FICO.
Their scores are between 300 and 850. Your particular person quantity is decided by info discovered in your credit score report.
And there are three main credit score bureaus that present these stories (Equifax, Experian, and TransUnion). So you’ll be able to have three totally different credit score scores at any time. Granted, the scores gained’t usually differ that a lot from one another.
The next items of knowledge decide your precise rating (courtesy of Wells Fargo):
- 35% cost historical past. How dependable you might be. Late funds harm you.
- 30% quantities owed. How a lot you owe and the way a lot credit score you will have accessible, or your “credit score utilization charge.” And the formulation for it’s easy: (how a lot you owe) / (complete credit score accessible).
- 15% size of historical past. How lengthy you’ve had credit score. Older accounts are higher as a result of they present you’re dependable.
- 10% what number of kinds of credit score. In case you have extra strains of credit score open, the higher your rating will probably be.
- 10% account inquiries. What number of occasions you will have or a lender has checked your credit score background.
850 is technically the right credit score rating … however any rating between 800 and 850 is commonly stated to be “good” as properly.
How? Check out the chart under:
Issues like approval for loans and bank cards and rates of interest gained’t differ when your rating is within the 800s.
Additionally, it’s very uncommon to get 850. In truth, just one in 9 People have a credit score rating of 800 or greater. And simply 1% have a credit score rating of 850 (Supply: USA Right this moment).
3 classes from good credit score scores
It’s not inconceivable although. You CAN attain an ideal credit score rating by means of surprisingly easy techniques.
That’s why I talked to a few folks inside this good credit score rating vary and had them break down how they bought their good credit score scores.
Enable me to introduce you to them now:
Meet Randall, the finance trainer
Randall has a credit score rating of 842. He lives along with his spouse and toddler simply southwest of Salt Lake Metropolis within the city of Herriman, Utah. There, he does God’s work as a highschool finance trainer.
Meet Derek, the supervisor
Derek has a credit score rating of 829 however his credit score was … properly, lower than good. “I used to assume that bank cards have been a sucker’s wager,” he explains. “So I paid payments utilizing checks or auto-debit. Whereas my credit score rating didn’t look horrible, I had basically no credit score historical past other than utility payments and a pair financial institution accounts.”
This all modified someday when he wanted to purchase a automotive. “I wanted to get a automotive mortgage of a reasonably modest quantity,” he says. “NOPE, not with no loopy rate of interest. My rating wasn’t unhealthy, however the lack of historical past was a significant issue. So I utilized for an honest bank card, simply to see the place the ground was. That was declined. At that time I began studying up on methods to construct up nice credit score.”
Meet Harry, the product marketer
Harry has a credit score rating of 830. He bought his begin constructing credit score early in highschool when his mother and father put him on as a certified consumer on their bank card.
“They advised me one thing I’ll always remember,” he remembers. “‘Credit score is a instrument. Deal with it like a loaded gun.’”
After talking with the three of them, I’ve distilled their insights into three classes to assist anybody enhance their credit score rating:
Excellent credit score rating lesson #1: Begin small and scale
Randall, the trainer:
“I bought a bank card after I turned 18 and didn’t know precisely what I used to be doing with it. My mother and father each filed chapter twice so I discovered precisely what NOT to do from them.
“Then in school, I became a dollar-to-dollar Excel spreadsheet type of man … I’ve my entire private finance system automated to repay my card every month and I maintain my accounts lively — even the cardboard I had after I was 18. Then someday, I spotted I had a credit score rating within the 800s.”
Derek, the supervisor:
“I went to my financial institution and bought a secured bank card of $500. Then I had it auto-pay out of my checking account. I paid all payments on time, no exceptions.
“I additionally set an alert to remind me each six months to request a rise on my spending limits on my bank cards. As soon as I had over $100k in accessible credit score, my utilization was at all times rated ‘Wonderful’ on my credit score monitoring app so I ended worrying about it.”
Harry, the marketer:
“After I went from 20 accounts opened in my lifetime to 22, that was the magic quantity that pushed me over the sting to have a near-perfect rating. I believe it additionally helped that I began constructing credit score in highschool when my mother and father made me a certified consumer.”
Excellent credit score rating lesson #2: Be boringly constant
Randall, the trainer:
“I imply this within the nicest method attainable: For those who simply don’t be a dumbass, your credit score goes to be nice. Don’t purchase shit you don’t want and pay your payments, then you definately’ll have credit score rating. That’s what I did and I bought an incredible credit score rating due to it.”
Harry, the marketer:
“For those who do the fundamental stuff — automated funds, getting and constructing credit score every month — you’ll have to attend a number of years however it’s going to ultimately work out. For me, I don’t even care about what my credit score rating is. I don’t care in any respect. Proper now, I’m targeted on work, and my household, and every part else. The credit score rating doesn’t even come up on my radar after I do my monetary planning.”
Excellent credit score rating lesson #3: Give attention to the 80/20
Randall, the trainer:
“Repay a minimum of some of your assertion every month. Don’t get me improper. It is best to do all you’ll be able to to pay your bank card assertion in full. However in the event you don’t manage to pay for for one cause or one other, it is best to nonetheless pay a small quantity. Some cost is healthier than nothing with regards to your credit score rating.”
Derek, the supervisor:
“Implement a schedule for every part. This takes some time. Payments must be paid, credit score must be elevated, and so forth. I set recurring reminders on my smartphone and implement autopay.”
Harry, the marketer:
“So long as you’re making automated funds every month and you’ve got a low credit score utilization ratio, not one of the relaxation actually issues.”
Enhance your credit score rating = Large Win
Take the time to start out enhancing your credit score rating utilizing the 4 techniques outlined above — and that can assist you much more, I’d wish to give you one thing: The primary chapter of my New York Instances best-seller “I Will Educate You to be Wealthy.”
It’ll assist you to faucet into much more perks, max out your rewards, and beat the bank card firms at their very own sport.
I need you to have the instruments and word-for-word scripts to combat again towards the massive bank card firms. To obtain it free now, enter your title and e-mail under.