

Discovering the fitting financial savings account can get you an additional $200 without spending a dime this 12 months.
Relying in your stability, it may make you much more cash.
Let’s say you’ve got $10,000 to place into top-of-the-line on-line financial savings account.
How a lot would that flip into at a giant financial institution financial savings account? Most massive banks have an APY (annual proportion yield) of 0.15% or much less. After a 12 months, your account can be price $10,015. Not a lot of a acquire there.
I really like getting cash for nothing, however even I’ve a tough time getting excited over an additional $15.
Now let’s say you’re taking that very same $10,000 and put it into an internet high-yield financial savings account with an APY of two.25%.
After a 12 months, you’ll have $10,225.
That’s $225 for doing completely nothing. Everybody wants some further money available for an emergency fund anyway. Why not get as a lot as you may whereas it sits there? All it takes is opening the fitting account.
The very best on-line financial savings accounts
We’re going to do a deep dive into what to search for, which accounts are finest, easy methods to get the best APY, and methods for optimizing your financial savings accounts.
Right here’s a breakdown of what we’ll cowl:
What Issues When Selecting an On-line Financial savings Account:
- Person Expertise and Firm Status
- Charges
- Comfort
- FDIC Insurance coverage
- APY Charges
On-line Financial savings Account Critiques:
The 4 Step Course of to Selecting an On-line Financial savings Account
If you wish to skip all of that and open an account proper now, these excessive curiosity on-line financial savings accounts had been our high rated:
You’ll be pleased with any of them. My private favourite is Ally.
What issues when selecting an internet financial savings account
Right here’s how we consider these accounts.
Person expertise and firm fame
Good on-line and cell apps make an enormous distinction lately, however it doesn’t matter as a lot while you’re in search of a excessive curiosity on-line financial savings account.
It must be ok however not nice.
Why?
As a result of we hardly ever log into financial savings accounts. They normally have limits of with the ability to withdraw from them as much as 6 occasions monthly. By definition, they’re not meant for use commonly.
Having fast and easy accessibility to your funds is much less necessary than working with an organization that has a dependable fame.
Whereas most prospects can entry their high-interest fee accounts rapidly in an emergency, not all monetary establishments are created equal. We skipped firms that scored lower than 65 % of the Harris Ballot Company Status Rankings like Wells Fargo, Goldman Sachs, and Financial institution of America. We additionally factored in main scandals during the last 5 years.
Charges
For on-line financial savings accounts, it’s completely important that you just get an account with none upkeep charges. Month-to-month upkeep charges was once frequent. Fortunately, most accounts have finished away with them.
On any good financial savings account, you’ll hardly ever run into charges throughout regular utilization. However even on the very best accounts, it’s potential to set off charges for sure occasions:
- Returned deposit gadgets
- Overdraft gadgets paid or returns
- Extreme transaction charge (like going over 6 withdrawals monthly)
- Expedited supply
- Outgoing home wires
- Account analysis charges
We’ve made positive to not embody any banks in our record which have upkeep charges. However you ought to be conscious of a few of these different charge gadgets that do exist on each account.
Comfort
What we take into account to be “handy” with financial savings accounts falls into two buckets relying on the place you might be in your personal private finance journey.
Whenever you’re constructing financial savings for the primary time, it’s important to get an account with no minimal stability requirement. A $5 required stability or one thing like that’s effective, you simply don’t need to have to fret a couple of increased one.
Don’t put up with any account that requires a large minimal stability. There are such a lot of choices that don’t have any stability necessities in any respect. That is the very last thing you ought to be fearful about within the early days, particularly if an emergency comes up and it’s essential to withdraw money.
Afterward, what you take into account to be handy sometimes modifications.
When you’ve constructed sufficient of a money buffer for your self, you’ll care quite a bit much less about minimal balances. As a substitute, your accounts, playing cards, and banks have all gotten difficult sufficient that simplicity issues much more than it used to. At this stage, some of us will go for a decrease APY as a way to consolidate their accounts and make the whole lot extra manageable.
Is that this the optimum technique to get each ounce of development out of your money? No, it isn’t. However the further piece of thoughts could be properly price the associated fee. If this sounds interesting to you, examine to see if the financial savings account at your important financial institution has a ok APY with none upkeep charges. If it does, it could possibly be the best choice.
FDIC insured
Don’t ever take into account an internet financial savings account that’s not FDIC insured. Which means that the account is assured by the federal authorities as much as $250,000 per depositor. If one thing horrible ought to occur to the financial institution, the federal authorities ensures you’ll nonetheless get entry to your stability, as much as $250,000. That is per depositor, so the $250,000 contains the mixed stability of all of your financial savings accounts on the similar financial institution.
Nearly each financial savings account is FDIC insured. It’s been a normal follow for a very long time. However maintain a detailed eye on this any time you’re contemplating an modern or distinctive strategy to storing your money.
For instance, some of us will retailer their money in a cash market account, which operates quite a bit like a financial savings account. Cash market accounts are normally FDIC insured. However cash market funds, which you place money into from a brokerage account, are usually not FDIC insured. A delicate but important distinction throughout tenuous occasions.
One other instance: Robinhood tried to roll out a checking account that promised a 3% APY. That’s a checking account paying increased curiosity than any financial savings account that was out there on the time, by nearly 1%. Sounds superb proper?
It got here with quite a few catches, one in all which was that it wasn’t FDIC insured. With out the FDIC insurance coverage, we don’t take into account the upper APY definitely worth the danger.
Our stance is that each greenback of our financial savings needs to be lined by the FDIC, even when the stability is excessive sufficient that we’ve got to separate it up between a number of financial savings accounts.
All the accounts that we overview beneath are FDIC insured. Simply maintain a watch out for this when you’re exploring an atypical strategy to storing your money.
APY charges
APY charges — the annual proportion yield — are the principle distinction between financial savings accounts. The upper your APY fee, the extra money that you just get mechanically each month.
APY charges throughout saving accounts usually fall into 3 tiers.
Large financial institution financial savings account APYs
For the overwhelming majority of massive financial institution financial savings accounts, the APY is horrible. Large banks assume that you really want a financial savings account alongside together with your checking account, so that they don’t do something to entice you for the financial savings account itself. Even when loads of on-line high-yield financial savings accounts are providing an APY of two%, massive banks would possibly solely provide a 0.15% APY. On a financial savings stability of $10,000, that’s a distinction between making $200 a 12 months versus $20 a 12 months.
This doesn’t apply to ALL massive banks, however most of them do fall into this class. So maintain a watch out for these. Except you actually need to maximize comfort by consolidating accounts and taking a decrease APY, it’s price discovering an account with a better APY.
Excessive yield financial savings account APYs
Excessive yield financial savings accounts have grow to be extraordinarily in style. These banks don’t have branches, they’re 100% on-line. Since save quite a bit from not having bodily places, they cross the financial savings onto you with a better APY.
Ally and American Specific are two of the preferred banks on this class.
The APY additionally stays up to date over time. Again in the course of the monetary disaster, the Federal Reserve dropped rates of interest to 0% and most excessive yield financial savings accounts had APYs of 0.5-0.7%. Because the Federal Reserve elevated rates of interest, these similar accounts additionally elevated their APY. Every time rates of interest enhance, you’ll get these will increase mechanically from these accounts. No must always change between accounts and chase the very best fee.
Leading edge APYs
At any given second, there are a couple of banks which can be pushing the APYs increased than anybody else. They’re doing this as a promotional technique to draw extra prospects. A few of these banks maintain tempo with altering rates of interest, a few of them don’t.
Whereas we don’t take into account it definitely worth the effort to chase an additional 0.1% on our APY, these banks are an possibility when you’re trying to maximize the APY in your financial savings.
On-line financial savings account critiques
Right here’s the lowdown on the preferred on-line financial savings accounts.
Axos financial savings account
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.30%
The APY is far decrease than different high-yield financial savings accounts — it’s common at finest. There’s no cause to open an Axos account except you’ve already maxed the FDIC limits on each different high-yield financial savings account and must get a decrease APY to horde all of your money.
I like to recommend selecting one of many different accounts from this record.
Uncover on-line financial savings account
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.60%
Uncover’s APY is fairly robust. Not fairly the highest, however it’s actually shut.
And when you occur to have a Uncover card or checking account, preserving your accounts in a single place makes the whole lot quite a bit less complicated.
You probably have one other Uncover account, undoubtedly get a Uncover financial savings account.
HSBC
HSBC has a couple of totally different financial savings accounts.
HSBC Premier Financial savings
- FDIC insured: Sure
- Minimal stability: $100,000 throughout your deposit accounts and funding balances. For those who go beneath this stability, there’s a $50 month-to-month charge.
- Upkeep charges: None
- APY: 0.15%
The HSBC Premier accounts are for purchasers who’ve massive deposits at HSBC. Sadly, the APY is terrible. An APY that low with a minimal stability of $100,000 is sort of insulting.
It is a good instance of a basic massive financial institution financial savings account. A bunch of constraints with a horrible APY. Skip these accounts fully.
- FDIC insured: Sure
- Minimal stability: $1
- Upkeep charges: None
- APY: 1.85%
HSBC does have a high-yield financial savings account with a aggressive APY. Usually, I’d advocate this account as a important contender.
However HSBC is only a horrible financial institution. Each interplay with them is harder than it must be. The one cause I’d ever take into account opening an HSBC account if I wanted an enormous, worldwide financial institution for some cause.
Although this account seems to be nice on paper, you’ll remorse it in case your expertise is something like ours.
Ally financial savings account
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.6%
We’re enormous followers of Ally. They’ve grow to be one of many main high-yield financial savings accounts.
Sure, Ally doesn’t technically have the best APY, however it’s darn shut. And so they replace their APY usually. So if rates of interest proceed to rise, you’ll get a better APY with out having to do something.
Their account UI is fairly slick too, and it’s at all times bettering.
I’ve an Ally account myself.
Be at liberty to cease studying right here and open an Ally account proper now. You received’t remorse it.
Capital One 360 Financial savings
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.7%
Capital One used to have an APY that lagged the remainder of the market, making it a sub-standard alternative. You’d have to make use of one other financial institution or their Capital One 360 Cash Market account to get a aggressive APY.
Now they’ve an APY that’s simply nearly as good as most banks. It’s one of many high contenders.
Particularly in case you have Capital One bank cards, it’s very nice to maintain the whole lot at one financial institution.
Marcus by Goldman Sachs
- FDIC insured: Sure
- Minimal stability: None, however there’s a deposit restrict of $1,000,000 for all of your financial savings account and CDs
- Upkeep charges: None
- APY: 1.7%
Goldman Sachs jumped into the high-yield financial savings account house with one of many highest APYs.
They do restrict deposits to a complete of $1,000,000, however that’s not a serious concern. You’ll need to break up up your money balances throughout a number of banks to get all of it FDIC insured anyway.
For those who’re in search of your first high-yield financial savings account, it is a implausible possibility.
American Specific financial savings account
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.7%
American Specific was one of many first to introduce a high-yield financial savings account, and it’s been round for awhile now.
Today, the APY is barely decrease than among the rivals. Whereas American Specific does replace their yields steadily, they’re at all times 0.10-0.20% off the best charges. Whereas it’s nonetheless a terrific possibility, I’d select one of many different accounts because of this alone.
One different caveat: the American Specific financial savings account isn’t built-in into the identical login account because the American Specific bank cards. Even in case you have each, it seems like having two totally different banks. There’s no further simplicity from attempting to consolidate.
Barclays financial savings account
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.7%
One other nice possibility. Nice APY, no upkeep charges or minimal balances — you may’t go incorrect with a Barclays on-line financial savings account.
Synchrony financial savings account
- FDIC insured: Sure
- Minimal stability: None
- Upkeep charges: None
- APY: 1.7%
Synchrony can also be a terrific possibility. The APY is likely one of the highest and has no minimums or upkeep charges.
Vio Financial institution
- FDIC Insured: Sure
- Minimal Deposit: $100
- Upkeep Charges: None
- APY: 1.85%
This account gives increased returns as a result of the financial institution has no bodily places. They provide a aggressive APY with a low minimal deposit. You’ll need to look out for the $5 charge to obtain paper statements and a $10 charge for any withdrawal over the allotted six transactions monthly.
Comenity Direct Financial institution
- FDIC Insured: Sure
- Minimal Deposit: $100
Upkeep Charges: None - APY:1.90%
Comenity Financial institution has aggressive charges and doesn’t cost a upkeep charge. Purchasers additionally get free ACH transfers, free on-line statements, free incoming transfers, and limitless deposits on their cell app or by way of ACH switch. They do cost for outgoing wire switch, official examine requests, and paper assertion charges. Comenity has an interest-earning restrict on balances of $10 million.
Residents Entry
- FDIC Insured: Sure
- Minimal Deposit: $5,000
- Upkeep Charges: None
- APY: 1.85%
Whereas Citizen’s Entry does have a better minimal stability to earn curiosity, the APY could be very aggressive, and so they rank excessive for his or her CDs as properly. Citizen’s Entry doesn’t have a cell app and so they don’t provide any checking accounts, so that you’ll have to separate your funds between two monetary establishments.
The 4-step course of to selecting the very best on-line financial savings account
- Examine the banks that you just presently have accounts with and see if they’ve a aggressive financial savings account. If the APY is similar to the accounts we listed above, stick together with your present financial institution.
- In any other case, decide an account from this record:
- Attempt to decide an account from a financial institution that you just foresee doing different enterprise with. For instance, Ally has automobile loans and Uncover has their bank cards.
- For those who’re nonetheless undecided, go together with Ally.
What about sub-savings accounts?
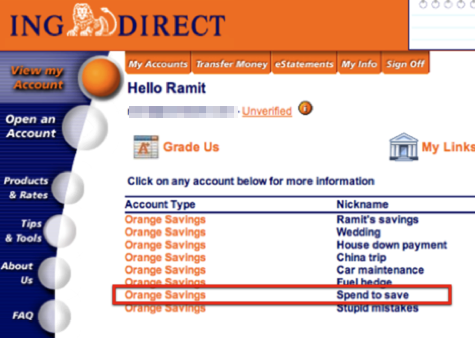
One in all our favourite financial savings account methods is to open “sub-accounts.” This permits us to simply price range for greater purchases by saving somewhat bit every month. We are able to additionally observe the whole lot by separating all of the accounts.
For instance, I’ve these classes in my very own financial savings account:
- Emergency fund
- Home downpayment
- Mini-retirement
- Christmas presents
- Annual trip
Every month, cash goes into every of those separate accounts with the automated transfers that I arrange. And I can simply see how a lot I’ve saved in direction of my targets.
Ramit’s financial savings accounts used to seem like this again earlier than ING Direct was purchased by Capital One:
Right here’s a extra present instance in Ally:
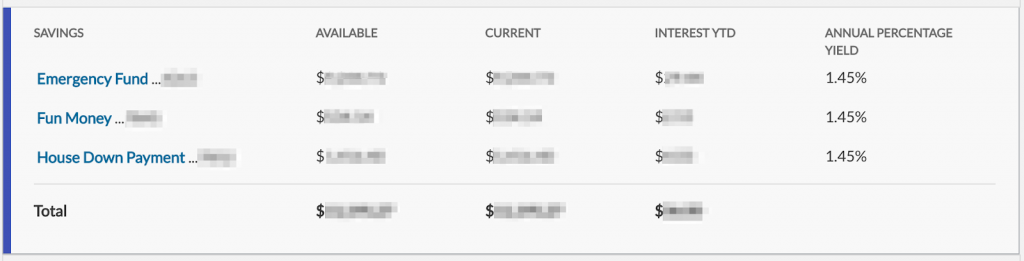
Some financial savings accounts will name these “sub-accounts,” and the whole lot will probably be a part of the identical financial savings account. It is a uncommon function to search out although.
For everybody else, merely open up a number of financial savings account underneath the identical financial institution login. You’ll be able to simply have 5-10 accounts on the similar financial institution. Then deal with every account for no matter saving class that you just like.
This implies you will get “sub-accounts” at any financial institution, even when they don’t have a “sub-account” function.
Don’t chase yields
Look, there’s at all times a financial institution that has a barely increased APY. Banks use it as a promotion technique to get extra accounts, so it’s at all times altering.
Commonly researching new APY charges, in search of that further 0.05% APY, opening accounts, and transferring cash everywhere wastes extra time than it’s price.
Don’t be a fee chaser.
Bear in mind IWT’s philosophy of massive wins. Concentrate on the key wins that actually transfer the needle and neglect concerning the small stuff. Chasing increased APYs on financial savings accounts undoubtedly falls into the “small stuff” class.
Choose a financial savings account that has a aggressive APY from a financial institution that you just belief for the long run. Then persist with that call and work on bettering different areas of your life.
Cash market accounts vs financial savings accounts
The distinction between cash market accounts and financial savings accounts could be fairly complicated.
That’s as a result of there’s no sensible distinction.
Listed here are the similarities:
- The APY tends to be the identical between each kinds of accounts.
- You’ll be able to withdraw as much as 6 occasions monthly.
- Some have ATM playing cards, some don’t.
- Some have minimums, some don’t.
- Each are FDIC insured.
Mainly they’re the identical account. In case your financial institution occurs to supply a cash market account with no upkeep charges, no minimal, and a aggressive APY, be happy to make use of it.
Now for the complicated half: cash market funds are utterly totally different. They’re a part of brokerage accounts and permit you to place money whilst you wait to speculate it. Since cash market funds are usually not FDIC insured, so it’s not behavior to retailer lots of money in them.
When to get financial savings accounts from a number of banks
For those who ask excessive internet price of us which financial savings accounts they’ve, typically they’ll record off half a dozen totally different banks.
At first, this is not sensible. Why all the additional complexity and totally different accounts?
There’s one cause: FDIC insurance coverage limits.
Most individuals are restricted to $250,000 price of insurance coverage at any given financial institution. Joint accounts and accounts throughout totally different classes (like retirement accounts) can enhance this restrict, however that solely goes up to now. You probably have a considerable amount of money, the one strategy to maintain it insured is to open up financial savings accounts throughout a number of banks.
That’s why of us will begin opening up financial savings accounts throughout a number of banks.
You probably have a number of financial savings accounts to handle, Max will mechanically transfer balances round your accounts to optimize for the best APY whereas preserving all of your money insured. They do cost a 0.08% annual charge for the service.
As for which accounts to open, we advocate beginning with these:
Any mixture of accounts which have robust APYs will work.